Skip to content
Skip to content

Practical automation guide · By Yes AI

Automate supplier bill payments with approvals

Published 5 min read

Paying suppliers usually means choosing which bills are due, building a batch in the accounting software, loading it into online banking and approving it there. Most of that can be prepared automatically, while releasing money needs controls that a fraudster cannot get around by sending an email. This guide covers both parts.

Quick answer

A supplier payment run can be automated by selecting approved bills due before the next run, checking each supplier's bank details against the verified record, building a batch payment in Xero or a bank file, and sending the batch to two authorised people to release in online banking. Any change to a supplier's bank details is confirmed by phone, on a number already on file, before that supplier can be paid.

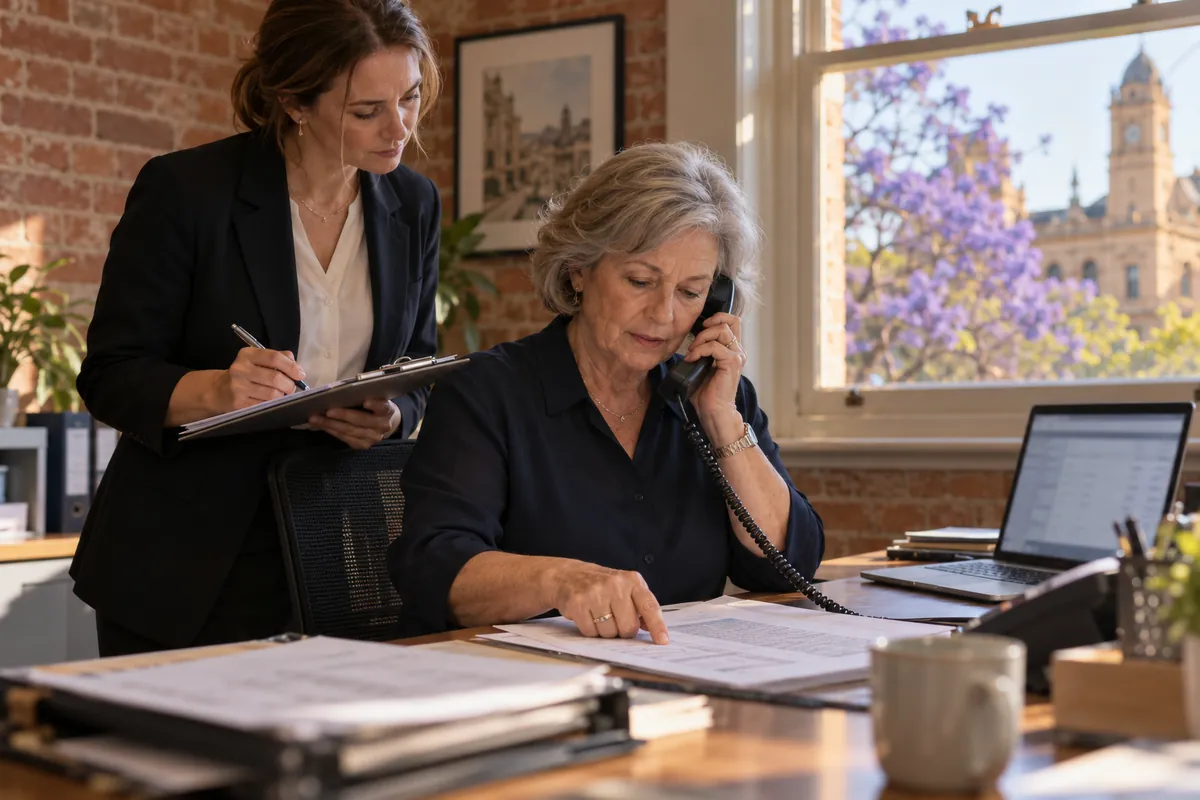
Finance officer in an Adelaide office on the phone confirming a supplier's bank details against a printed record

Which steps of a payment run can be automated?

The preparation can be automated and the release should stay with people. The workflow selects bills that are approved, due before the next run and not on hold, groups them by supplier and totals them against the bank account they will be paid from. It then builds the batch and drafts remittance advice. Two authorised people review the total and release it in online banking. The automation account should have no rights to release payments at all, so a fault or a compromised credential cannot move money on its own.

  • Select approved bills due before the next run.
  • Exclude bills that are disputed, on hold or missing approval.
  • Check each supplier's bank details against the verified record.
  • Build the batch payment and the bank file.
  • Draft remittance advice for each supplier.

What does Xero's batch payment allow?

A Xero batch payment bundles several bills into one payment, so one line on the bank statement reconciles against one transaction in Xero. Through the API, batch payments can only be made in the organisation's base currency, cannot mix sales invoices with bills, and cannot include credit notes, prepayments or overpayments. In practice, apply supplier credit notes to their bills before the run, and pay foreign currency bills separately. The Details field, which is sent to the bank as the reference for the batch, is limited to 18 characters, so agree a short reference format.

How should bank detail changes be handled?

Business email compromise is when a criminal gains access to a business email account and uses it to trick contacts into sending money to accounts the criminal controls. The Australian Cyber Security Centre advises an approval process for any request to change payment details, and verifying the request by calling the sender on a verified number, never one taken from the email. Build that into the workflow so it cannot be skipped.

  • Supplier bank details change only through a change request in the workflow, never by editing the record directly.
  • A change puts the supplier on hold until a verification call is logged.
  • The call uses the phone number already on file, not the one in the request.
  • A second person confirms the call record before the hold is lifted.
  • Every invoice is compared with the stored bank details, and any difference is flagged.

Does Confirmation of Payee help?

It adds a check at the bank. Since July 2025, Australian banks have rolled out Confirmation of Payee, which compares the account name you enter with the BSB and account number when you add or edit a payee, and shows a match, close match or no match result. For business accounts the account name may be shown whatever the result. Use it when you set up a new supplier as a payee in online banking. It does not replace the phone call to the supplier, and you should ask your bank whether its checks apply to bulk payment files as well as single payments.

Who should approve and who should release?

Separate the duties so no single person can both change where money goes and send it. The person who approves a bill confirms the goods or services were received at the agreed price. The person who updates supplier bank details should not be able to release payments. Release in online banking should need two authorised people; ask your bank how to set up dual authorisation on the account. Write these roles down, including who covers each one during leave, because payment runs that wait for one absent person tend to get approved by whoever is available.

How are payments recorded and suppliers told?

After the bank processes the batch, the workflow marks the bills as paid in Xero through the batch payment, so the single bank statement line reconciles against it. It then emails remittance advice to each supplier's accounts address already on the record, listing the bills paid and the amounts. Store the batch file, the approval records and the bank's confirmation together. If the bank rejects part of a batch, for example because an account number is invalid, the workflow reopens those bills and puts the supplier on hold until the details are verified again.

Who does what in an automated payment run

StepAutomationPersonControl
Select billsLists approved bills due before the next runRemoves disputed or held billsOnly approved bills are eligible
Check bank detailsCompares invoice details with the supplier recordCalls the supplier on the number on file for any changeA change holds the supplier until verified
Build the batchCreates the batch payment and bank fileReviews the total against the cash forecastBase currency only; credits applied first
ReleaseNoneTwo authorised people approve in online bankingThe automation has no release rights
Record and adviseMarks bills paid and emails remittance adviceChecks the bank line matches the batch totalBatch file and approvals stored together

Practical checklist

  • The automation's accounts cannot release payments in online banking.
  • Supplier bank details can only change through a logged verification call.
  • Bills with unapplied credit notes are fixed before the batch is built.
  • Foreign currency bills are excluded from the batch and paid separately.
  • Two people release every batch, and neither can change supplier bank details alone.
  • Remittance advice goes only to the accounts address already on the supplier record.

Common questions

Can the automation pay suppliers directly through a bank API?

Some banks offer payment APIs for business customers, but this guide assumes release happens in online banking. Whichever route you use, keep release rights with people and require two approvals. An automation that can both prepare and send payments is a single point of failure for fraud and for software errors.

What if a supplier emails new bank details with an invoice?

Treat it as a change request. The workflow places the supplier on hold and creates a task to call the supplier on the number already on file. Do not use the phone number, email address or link in the message, because those may belong to the fraudster. Only after the call is logged and confirmed by a second person is the record updated.

How often should the payment run happen?

Weekly or fortnightly runs are common in small businesses. Pick a fixed day that suits your suppliers' terms and your cash flow, so the cash forecast can plan around it. A fixed day also makes an unexpected urgent payment request easier to notice, which helps when a fraudster pushes for speed.

Can we still pay an urgent bill outside the run?

Yes, through the same controls. An off-cycle payment should still need an approved bill, a verified bank record and two people to release it. Record the reason it was urgent. Urgency is a common feature of payment redirection attempts, so an off-cycle request from a supplier whose details recently changed deserves a second look.

Does this replace our accountant or BAS agent?

It does not. The workflow handles preparation, controls and record keeping. How bills are coded, how GST is treated and how payments are reported remain matters for your accountant or registered BAS agent. Ask them to review the payment run design before it goes live, particularly the handling of credit notes and part payments. This guide is administrative guidance only.

Sources and further reading

Continue planning

Turn the guide into your workflow

Bring one process, the systems it touches and the exceptions your staff handle. We can discuss approval boundaries, recovery steps and the evidence needed before changing live operations.